• Home
  • Blog
  • Contact
    • Location
  • About
    • Libby Guthrie
    • Ken Guthrie
    • Brittany Armenta Perez
  • Search the MLS
  • Sell
    • Sell My House
    • What’s My Home Worth?
  • Buy
    • Search the MLS
    • Home Buyers Guide – How to Avoid Costly Mistakes When Buying a Home
    • Frequently Asked Questions of Home Buyers
  • Reviews
    • Leave Your Review
  • FAQs

Guthrie Group Homes

Real Estate

Call Guthrie Group Homes, Real Estate at (925) 628-2436 | DRE #01117537 Guthrie Group Homes, Real Estate - Keller Williams East County
Real Estate - Home » Blog » Financing » How Credit Cards Affect Your Mortgage Application

How Credit Cards Affect Your Mortgage Application

May 15, 2017 By Ken Guthrie Leave a Comment

Hands holding credit card and using laptop.

So you think you’re finally ready to buy a house, but you have some credit card debt you’re thinking of paying off first. You’re wondering if your credit cards will affect your ability to get a mortgage.

That’s a smart thing to wonder! 

Getting your credit in order before you apply for a home mortgage can save you big bucks in the long run, but also help you avoid disappointment from getting turned down by lenders.

When it comes to understanding how credit works, there is a lot to know and understand, so in this article, we’ll just talk about credit in relation to your credit cards.

One of the most important things to know it the better your credit, the less you’ll pay for your mortgage.

Start out by getting a free credit report and score from CreditKarma.com or CreditSesame.com. Both sites are free to join and you can check your credit as often as you want without affecting your credit score. When you apply for a new credit card, a car loan, or a home loan, you’ll get what’s called a “hard inquiry” on your account.  These hard inquiries can affect your score negatively and you want to avoid them as much as possible, especially when you are thinking of applying for a mortgage.

Once you have your credit score (aka Fico Score) and report, you need to understand that not all lenders will use the same methods to determine your credit score. So just because you have a good score of 720, doesn’t mean that is the score your lender will use. There are a variety of credit models that different lenders use, and the only score that really counts is the one your lender uses. So, for instance, CitiBank may give you one score, while Wells Fargo may give you a very different score. In addition, there are 3 main credit bureaus that track and report your credit scores differently, Experian, Equifax, and TransUnion. The bottom line is, good credit scores are earned, not given.

Here are a number of factors that make up your Fico score

  • Your payment history – do you pay on time?
  • Debt utilization – how much of your credit do you use?
  • Length of credit history – how long have you had your credit cards?
  • Types of credit – do you have other types of credit like a car loan or personal loan?
  • Inquiries for new credit – do you frequently apply for new credit cards?

Here’s how to manage those credit factors:

  1. Always make your payment on time, or early. Avoid paying at the last minute.
  2. Keep your debt utilization to 30% or lower. In other words, if you have a credit limit of $1000, avoid having more than $300 charged at a time.
  3. The longer your credit history, the better. So even if you have cards that you have paid off, do not cancel the card! They add to the length of your history.
  4. A variety of types of credit and credit cards from different banks can make you a more attractive borrower.
  5. Again, avoid applying for credit for the sake of it, or just to get a new credit card.

It’s a delicate balance of establishing your credit, and not using it too much. Sounds pretty counter-intuitive to me, so it’s easy to make mistakes.

You May Also Enjoy...  Your Credit Score - More Important Than Just For Mortgages

So now you know your Fico score and some of the basics on what your score is based on. What should you do to get ready to apply for your mortgage?

Here are some guidelines to follow:

Avoid charging more on your credit cards, keep the balances as low as possible.

Don’t apply for, open or close any credit accounts.

Do NOT buy a car, a boat or an RV. If you want to qualify to buy a house, that needs to be your top priority with your credit. And please don’t buy anything for your new home until the deal is done and you’re moving into your new house.

Don’t cosign any loans for friends or family.

Don’t do any debt or credit card debt consolidation.

If there are any discrepancies on your credit reports, try and sort them out before you apply for a mortgage.
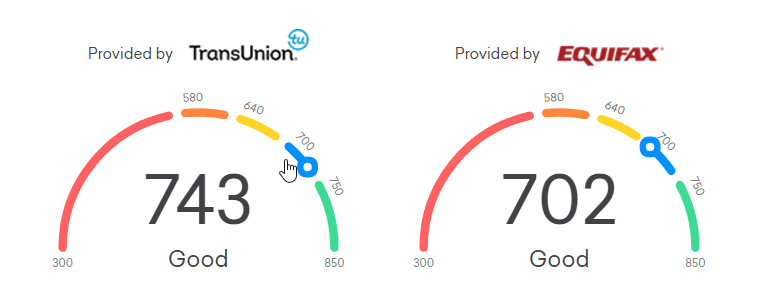
Examples of Credit Scores from TransUnion and Equifax

If you’re not sure what to do, ask a trusted financial advisor or lender. If you don’t have a lender you trust, ask for a referral from you real estate agent. Having someone to work with who has your best interests at heart will save you time, money, and heartache.

Keep in mind that this article is not the end all be all in credit advice. I guarantee your needs and circumstances will vary. The best way to take care of yourself financially is to do your homework, learn as much as you can, then consult a professional. If something doesn’t sound right or feel right, get a second opinion.

And of course, here is our disclaimer.
IMPORTANT NOTICE: We are not attorneys, tax or credit professionals. Any comments we make in regards to tax/legal/credit issues are of a general nature and should not be relied upon as such. Please seek expert counsel from the proper professional in these areas for specifics to your situation.


Share
Tweet
Pin
Share
Pocket
Buffer
0 Shares

Filed Under: Financing Tagged With: Credit, Credit Cards, Mortgage

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

This site uses Akismet to reduce spam. Learn how your comment data is processed.

Find Us on Social Media

Facebook
Facebook
fb-share-icon
Instagram
Pinterest
YouTube
YouTube
LinkedIn
LinkedIn
Share
Twitter
Follow Me

Our Most Popular Content

  • First-Time Home Buyer TipsFirst-Time Home Buyer Tips I’ve put together 15 First-Time Home Buyer Tips for you
  • Trilogy at Rio VistaTrilogy at Rio Vista Over 55 Community Have you been thinking about moving to a senior
  • A Homeowners Guide to Home Insurance A Homeowners Guide to Home Insurance Does Your Insurance Cover That? No one likes to
  • Real Estate - Home » Blog » Real Estate » You Just Listed Your Home, Now What? You Just Listed Your Home, Now What? You Just Listed Your Home, Now What? While listing and selling your home can feel
  • What $500,000 Will Buy You In Brentwood, CA vs. San Jose, CA What $500,000 Will Buy You In Brentwood, CA vs. San Jose, CA OK, we all know that buying a home
  • How Much Is My Home Worth? How Much Is My Home Worth? Get a FREE home valuation from expert

Blog Topics

  • FAQ's
  • Financing
  • Home Buyers
  • Home Improvement
  • Home Sellers
  • Homeowners
  • Libby and Ken Recommend
  • Local Communities
  • Page
  • Real Estate
  • Seasonal
  • Transfer

guthriegrouphomes

Libby Guthrie, Realtor
@ Keller Williams 865-966-5005
🏡 Helping You Make the Move to Knoxville
📱 Cell: 865-364-0200
🏡 Good People, Great Homes!

5 Heating-Season Checks Worth Doing Now Heating 5 Heating-Season Checks Worth Doing Now
 
Heating season has a way of exposing the little things that were easy to ignore all summer. 🔧
 
Five checks worth doing now:
 
1️⃣ Check or change the filter — if your heating system has one, follow the replacement schedule in the owner's manual
 
2️⃣ Book service if it's due — it's better to find a small problem during a routine visit than during a no-heat call
 
3️⃣ Find the drafts — doors, windows, the attic hatch, anywhere pipes come through a wall. Weather stripping and a tube of caulk go a long way
 
4️⃣ Review the thermostat schedule — make sure it still matches when you're home, asleep, and away
 
5️⃣ Reverse the ceiling fans, if yours have a winter setting — clockwise on low helps circulate warm air back into the room
 
A short check now helps your heating system work the way it's supposed to all season.
 
Which one is still on your list? Let us know in the comments.
 
Libby Guthrie, REALTOR® 🏡 | Cell: 865-364-0200 | GGHKnoxville.com 
Keller Williams 865-966-5005 | Libby@GuthrieGroupHomes.com
Knoxville, Tennessee
 
#HomeMaintenance #HomeownerTips #RealEstateTips #WinterPrep
When Selling Is Simply the Better Move If you've When Selling Is Simply the Better Move

If you've been weighing whether to keep the house and rent it out, it's worth hearing the other side: plenty of the time, selling is the clearer call.
 
You need equity. If the down payment on the next home depends on this one's proceeds, that usually settles it. Stretching to carry two mortgages is where this decision goes wrong most often.
The numbers don't work. Rent that doesn't cover the carrying costs, with no strong case for appreciation, is a monthly subsidy to a house you no longer live in.
 
The house needs work. Deferred maintenance, an aging roof, old systems. Tenants don't defer those costs — they surface them.
 
Your home sells well right now. A softer headline market doesn't mean your specific house is sitting.
 
You don't want the job. Being a landlord is ongoing work, not a one-time decision. Plenty of owners run the numbers, see a decent hold on paper, and sell anyway because they'd rather have a clean break and a simpler life.
 
Keeping the house isn't a free option. It just doesn't come with a monthly bill that makes the cost obvious.
 
Link in bio
 
https://gghknoxville.com/keep-it-or-cash-out-selling-vs-renting-your-knoxville-home/
 
Libby Guthrie, REALTOR® 🏡 | Cell: 865-364-0200 | GGHKnoxville.com 
Keller Williams 865-966-5005 | Libby@GuthrieGroupHomes.com
Knoxville, Tennessee
 
#SellOrRent #HomeSelling #RealEstateTips #ListingYourHome
Follow on Instagram

Hours & Info – Guthrie Group Homes, Real Estate

[one-third-first]
Location
191 Sand Creek Rd #100,
Brentwood, CA 94513

Contact Us
info@guthriegrouphomes.com
Office: (925) 628-2436

Broker:
Keller Williams East County

Real Estate License
Lic #01117537
[/one-third-first][one-third]Hours
Monday - 9AM–5PM
Tuesday - 9AM–5PM
Wednesday - 9AM–5PM
Thursday - 9AM–5PM
Friday - 9AM–5PM

Weekends by Appointment
Call (925) 628-2436

See Location
[/one-third][one-third]
Real Estate Menu
How We Market Your House
Home Search
Blog
Sitemap
FAQs

[/one-third]

Search Here

Visit our Sister Site in Knoxville Tennessee

Libby Guthrie Real Estate, Knoxville TN
Libby Guthrie Realtor, Knoxville TN

Guthrie Group Homes, Knoxville TN

Discover the history, beauty, and affordability of the Greater Knoxville area. Each neighborhood in Knoxville has its own charm and is worth exploring to get a true sense of the city's diverse character!

  • Home
  • Contact
  • Location
  • About
  • How Much Is My Home Worth?

Copyright © 2026 · Guthrie Group Homes, Real Estate · Lic #01117537 · 925-628-2436 · Brentwood, Antioch and Oakley, California · Log in

If your home is currently listed or you are a buyer represented by another real estate agent, this website, article, or blog post is for informational purposes only.

It is not our intention to solicit the offerings or clients of other real estate agents or brokers.

All information on this site is deemed reliable, but not guaranteed.

Terms of Use  | Cookies Policy | Privacy Policy | Advertising Policy | Accessibility

Privacy & Cookies: This site uses cookies. By continuing to use this website, you agree to their use.

To find out more, including how to control cookies, see here: Cookie Policy